How to Build an Emergency Fund While Living Abroad

Key Take-Aways
- An emergency fund for expat families should typically cover 3–6 months of living expenses, adjusted for location and risk.
- Multi-currency planning is essential to protect against exchange rate fluctuations and access issues.
- Emergency funds should be split across accessible accounts, not held in a single country or currency.
- Consistent, automated saving habits are the most reliable way to build financial resilience abroad.
Living abroad changes how money behaves and how you deal with it.
That sounds abstract, but it becomes very real the first time you need quick access to cash and realize it is sitting in the wrong country, the wrong currency, or the wrong account.
Back home, building an emergency fund is fairly straightforward.
Abroad, it requires a bit more thought. Not complicated, just more intentional. Once you understand the moving parts, it becomes one of the most stabilizing systems you can put in place for your family.
Establishing a money safety net living overseas ensures that your international adventure does not turn into a financial crisis at the first sign of trouble.
Define What “Emergency” Means in Your Context
Before you start saving, you need clarity on what you are actually preparing for.
An emergency fund is not a travel fund or a buffer for lifestyle upgrades. It is there for events that disrupt your ability to operate normally – an emergency, in other words.
This often includes job loss, unexpected medical expenses, or sudden relocation needs.
For families, there is often an extra layer. You may need funds for last-minute international flights or temporary housing if plans change quickly.
Defining this upfront helps you avoid dipping into the fund for non-essential reasons.
Having this cash buffer is essential when choosing a homeschool curriculum while living overseas or managing other major life shifts.
Calculate Your True Monthly Baseline
Most advice around emergency funds suggests covering three to six months of expenses. That still applies, but you need to be precise about what “expenses” actually include.
This is the core of effective budgeting for expat savings.
Focus on your non-negotiables:
- Housing and utilities
- Food and basic transportation
- Healthcare expenses
Depending on your situation, you can also add things like:
- Insurance premiums
- Education-related costs
Expat budgets can be less predictable due to rent adjustments or school fees. It is worth building in a small buffer rather than aiming for an exact number.
This financial cushion allows you to focus on growth as an expat family, such as raising bilingual children without formal schooling.
Choose Where to Hold Your Emergency Fund
If all your money sits in one country, you are exposed to local risks. This might include banking restrictions, currency devaluation, or limited access during emergencies.
Banks can go under, they can restrict your access to YOUR money, they can just not pay out, the government can interfere, the government can take it, … all kinds of nasty scenarios can happen when you put your money in a bank.
Don’t be naive and assume that it can’t happen to you.
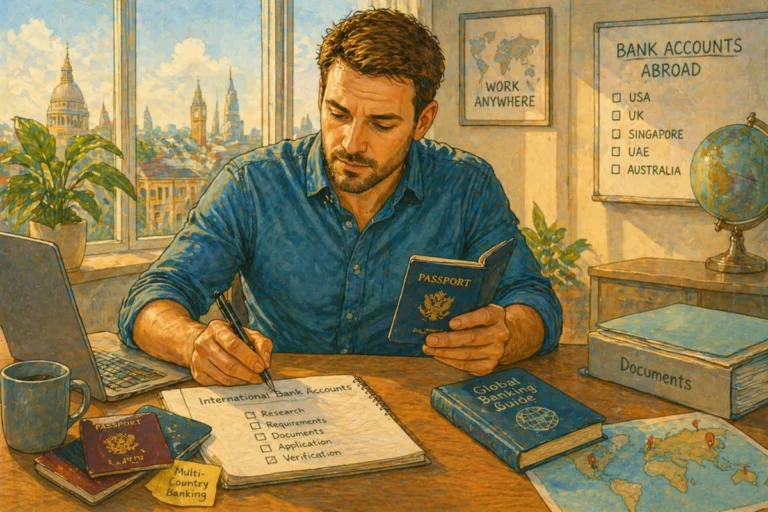
As such, a more resilient expat emergency fund setup involves diversification, across banks and across the world.
Many families split their funds across a local bank account for immediate access and an international account for stability.
Personally, I would strongly suggest you go much further. Having 4-5 bank accounts spread across the globe, plus a few digital, multi-currency accounts like Wise or Revolut, gives you a much higher level of financial freedom.
Think in Currencies, Not Just Numbers
Currency risk is something you cannot ignore when living abroad savings are involved.
If you earn in one currency but spend in another, exchange rates can quietly erode your fund’s value. A sudden shift can make your carefully calculated six months of expenses feel like four.
I’ve had this happen to me, in both directions. When the euro started growing in value vs the currency I was using here in Asia, I de facto became 20% more cash-abundant, without actually earning more.
However, when I then wanted to use the currency here in Asia to get currency in Latin America, I discovered the Latin American currency was at an all time high, and as such, I couldn’t have picked a worse time for the conversion!
A practical approach is to hold at least part of your fund in the currency you spend most often. Another portion can sit in a more stable or widely used currency like the USD or EUR.
Prioritize Liquidity Over Returns
An emergency fund is not an investment account. Its job is access, not growth.
That means keeping your funds in places where you can reach them quickly, without penalties or delays.
Accessibility always comes first. Avoid locking your emergency fund for expat families into long-term investments or fixed deposits with strict withdrawal rules.
In a real emergency, time matters more than returns.
I’d strongly suggest an account such as Wise, allowing you to access your funds wherever, whenever.
Automate Contributions to Build Momentum
Saving consistently is harder when your income or expenses fluctuate. Automation helps remove that friction.
Setting up regular transfers into your building emergency savings abroad plan creates momentum.
You do not need to build the entire fund at once. It is usually a gradual process that becomes easier as your system stabilizes.
Include a Buffer for Relocation Scenarios
One factor that often gets overlooked is the cost of leaving. For expat families, emergencies can sometimes mean relocating quickly.
This involves flights, temporary accommodation, and initial setup costs in a new location.
Including a relocation buffer in your expat emergency fund gives you options.
It allows you to make decisions based on what is best for your family. This is a standard recommendation for an emergency fund for nomads, and it goes double for expat families.
I keep about $5,000 aside, just for emergency flights. Hopefully we’ll never need it, but if we do need to make a sudden exit, we can.
Adjust Your Fund as Your Life Changes
Your fund is not a static number. As your family grows, your expenses change. Education costs increase and healthcare needs evolve.
Revisit your calculations once or twice a year to keep things aligned.
Keep It Separate From Everyday Finances
Blurring the line between your living abroad savings and your regular spending account is one of the fastest ways to undermine it.
Keeping the fund in a separate account creates a psychological boundary.
This separation is vital for maintaining peace of mind. It ensures the money is there when the unexpected happens.
Conclusion
In summation, building an expat emergency fund while living abroad is about creating stability in an environment that naturally has more variables.
By thinking in terms of access, currency, and flexibility, you can design a system that holds up under pressure.
When you are no longer reacting to uncertainty but are prepared for it, you gain the freedom to actually enjoy the life you are building overseas.