How to Open Bank Accounts in Multiple Countries

Key Take-Aways
- Opening bank accounts abroad depends heavily on residency rules, tax status, and identification.
- Many countries require proof of address, local tax numbers, or legal residency status.
- International banks and digital banks can simplify multi-country banking setups.
As an expat family, you probably now that managing bank accounts in multiple countries is a necessary part of life. You might earn income in one country, spend in another, and save somewhere entirely different.
That’s where expat multi-country banking comes in. It can give you flexibility, better currency control, and more stability when living internationally.
But it also comes with rules that vary widely depending on where you’re opening accounts. This is a core part of building long-term stability for your family’s future.
I’ve got bank accounts in several countries, across multiple continents, and it’s given my family and I a very solid financial basis. It wasn’t that hard, and today I’ll talk about some of the things to keep in mind.
I can strongly recommend Wise for international transfers to reduce currency losses as an expat. I’ve been using it for years and it offers the most bang for your buck, is easy to use and offers basically everything an expat dad needs.
Why Opening Accounts Abroad Is More Complex Than It Looks
On the surface, to open international accounts, you just need an ID and a deposit.
In reality, most banks operate under strict global financial regulations designed to prevent fraud, tax evasion, and money laundering.
These rules, such as the Basel III standards, affect how easily you can open accounts as a non-resident.
Most countries require banks to verify your identity, residency status, and source of funds.
For an expat father, this often means extra documentation compared to local residents. If you don’t have the right paperwork, your ability to manage money across multiple countries can be severely restricted.
That being said, in my experience, there’s a lot of leeway here. While there is always an overarching framework that banks have to stay in, some are more lenient and flexible than others.
For example, here in the Philippines, I’ve had several banks turn me down because I don’t have an employer, nor am I registered as a self-employed individual in this country. As such, I can’t provide them with pay-slips, and they can’t accept my money.
But after a bit of going back and forth, I found one that does accept my irregular situation, and I’ve been with them for close to a decade.
2. Understanding Residency and ID Requirements
Your residency status often determines your banking options more than your nationality. Many traditional banks require proof of local residency, such as a utility bill or a government-issued permit.
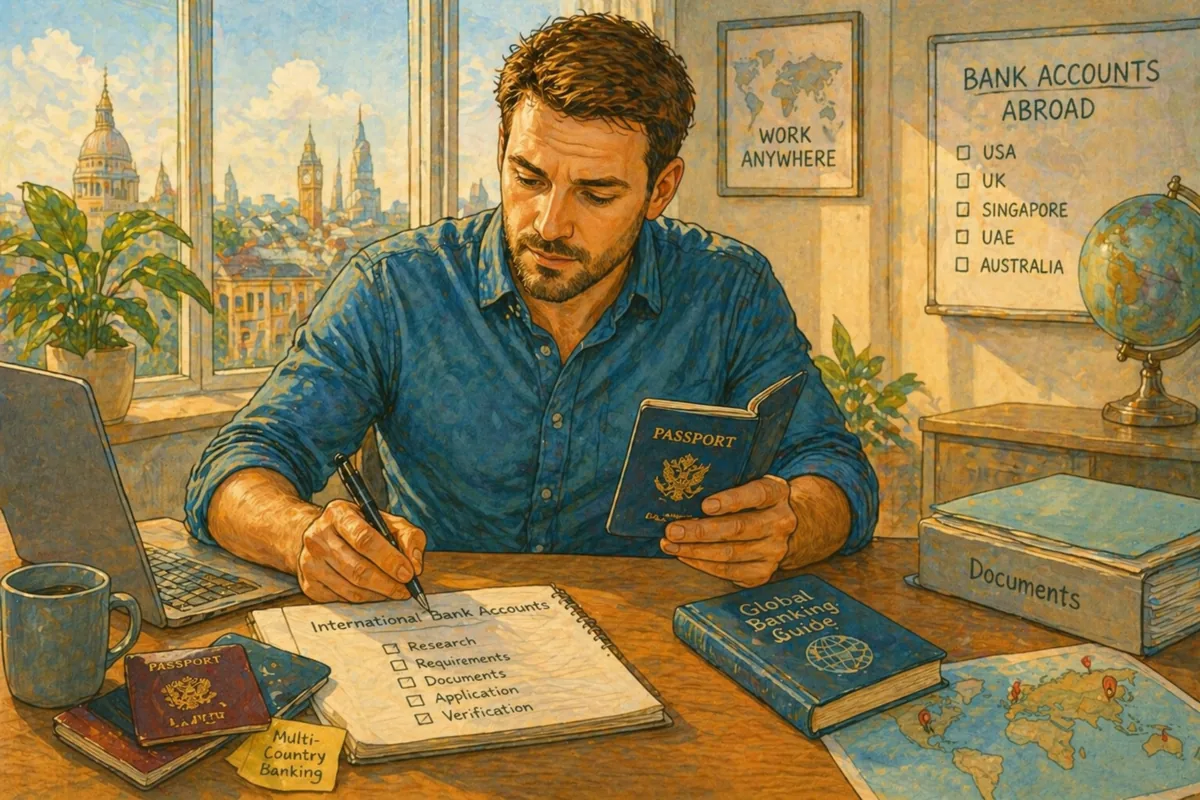
Requirements to open bank abroad typically include:
- Valid Passport: Your primary international identification.
- Proof of Address: A local rental contract or utility bill.
- Tax Identification Number: Necessary for global compliance reporting.
- Immigration Status: Proof that you are legally allowed to be in the country.
Without these, you may be limited to non-resident accounts which often have higher fees and lower transaction limits.
This is why many families prioritize learning how to get residency visas as their very first financial step in a new country.
Again, this varies from bank to bank, but for my next banking-ventures here in Latin America, I do fully expect to have to get my residency sorted first. No problem, because it’s what I wanted to do anyway.
3. Multi-Country Banking Options for Expats
There are generally three main ways to structure your banking across borders for expats:
- Traditional Local Banks: These offer full access to local payment systems (like PIX in Brazil or SEPA in Europe). They are the most stable but often have the strictest residency requirements.
- International Banks: Large global entities allow you to link accounts across borders, which is perfect for multi-currency family budgeting.
- Digital & Fintech Banks: Platforms like Wise or Revolut are often the best multi-currency bank accounts for nomads because they can be opened quickly and support dozens of currencies. These are what I would recommend for most expat dads, honestly. Unless you have a strong desire to get local bank accounts (like I do), sticking to international banking platforms usually is the best option.
| Bank Type | Best For | Main Drawback |
| Local | Paying local rent/utilities | Requires local residency proof. |
| International | Large transfers and wealth management | High minimum balance requirements. |
| Digital | Everyday spending and travel | May lack local “direct debit” features. |
4. Currency Considerations and Financial Discipline
One of the main advantages of holding multi-country bank accounts expat style is currency flexibility.
You can hold, receive, and spend money in local currencies, which reduces conversion fees. This is a vital skill when you are managing work, parenting, and travel.
However, you must be aware of exchange controls. Some governments limit how much money can be transferred out.
If you are investing as an expat (and I really hope you are!) these controls can affect your ability to move capital to your brokerage.
5. Tax Reporting and Legal Obligations
Holding money in multiple jurisdictions does not exist in a legal vacuum. Many countries require residents to report foreign accounts (like the FBAR in the US), even if the accounts are empty.
To avoid tax penalties, you need to ensure your banking options are transparent. Most banks now automatically share information with tax authorities under international agreements.
Ignoring these reporting obligations is one of the most common mistakes expat parents make, often assuming that out of sight means out of mind for the taxman.
However, there are still a few countries which do not automatically share your banking details, and I’d strongly recommend you make accounts there. I’m a very private person, and I think governments should mind their own business, and they definitely have no right to tax me on money from halfway across the globe.
Read More: If you are self-employed, knowing how to open foreign bank account structures is essential for managing a remote career while staying compliant with local employment laws.
6. A Practical Structure for Expat Families
Don’t just open accounts randomly. Think in layers to create a resilient system:
- The Anchor: A primary account in your main country of residence for daily life. I’d suggest at least two of these.
- The Safety Net: An account used to build an emergency fund in a stable, major currency (like USD or EUR).
- The Bridge: A digital multi-currency account for international transfers and travel.
This setup ensures that even if one account is frozen due to a compliance review, your family’s life doesn’t stop. You can still handle healthcare plans or pay for online education without interruption.
Final Thoughts: Control Over Complexity
In summation, learning how to open foreign bank account systems isn’t just a financial chore, it’s about building a stable international life.
Once you understand the rules behind residency and compliance, the process stops feeling like guesswork.
The goal is to create financial flexibility that supports your family’s life abroad without unnecessary friction.
When you have your expat multi-country banking under control, you can start providing an amazing life for your children.
I can strongly recommend Wise for international transfers to reduce currency losses as an expat. I’ve been using it for years and it offers the most bang for your buck, is easy to use and offers basically everything an expat dad needs.