Investing as an Expat: What Changes and What Doesn’t

Key Take-Aways
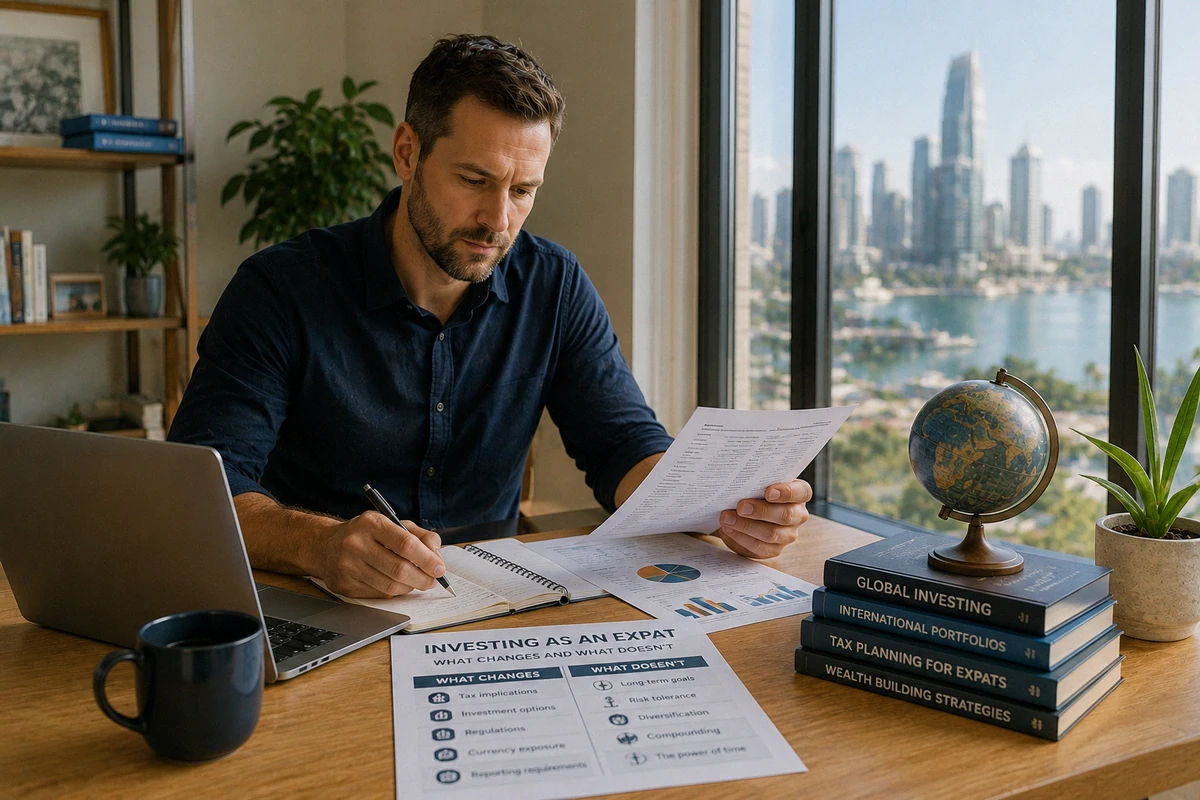
- General, core investing principles such as diversification, long-term discipline and patience, and cost control do not change when you move abroad.
- What does change is taxation (often in a good way!), reporting requirements, account eligibility, and currency exposure.
- Your investment access can vary by residency status, local regulations, and brokerage policies.
When you move abroad, a lot changes – I probably don’t have to tell you that!
The food. The language. The healthcare system. Even how you think about schooling and long-term planning for your family.
But when it comes to investing, the fundamentals remain surprisingly steady.
At least for me, when I moved halfway across the world (and then, a decade later, to yet another completely different continent), my investment strategy stayed the same.
What does shift are the administrative layers around your money: the tax treatment, the reporting rules, the currency dynamics, and the legal frameworks tied to residency and citizenship.
If you are building financial independence while raising a family overseas, understanding that distinction is critical and yes, it does come with more planning.
Fortunately, these aspects can work in your favour.
Successfully separating the operational noise from the constants is the first step toward how expat families manage money across multiple countries without losing your mind to paperwork.
Let’s look at what stays the same and what shifts when managing an international portfolio for expats.
What Does Not Change: The Core Principles
Let’s start with my favourite part: the core principles behind investing.
Why do I like it so much? Because it’s logical. The mathematics of investing does not care where you live.
- Diversification still reduces risk across asset classes.
- Long-term compounding still rewards patience.
- Excessive fees still erode returns.
- Emotional decision-making still damages portfolios.
These principles are supported by decades of financial research across global markets, and they’re what I structure my financial life around – and what I can definitely recommend you do too.
It’s what I help my clients achieve in my Nomad Long-term Financial Strategy service!
Broad market exposure, cost efficiency, and disciplined allocation remain foundational regardless of your physical address.
Understanding the importance of being invested over the long haul highlights why basic market participation matters more than geographic location.
Doesn’t matter if you move from Canada to Thailand or from Germany to Mexico: the idea of spreading investments across sectors and geographies remains sound and, if done correctly, a virtually guaranteed recipe for success in the long run.
Your passport does not rewrite basic financial theory, and mastering expat investing always starts with these unmovable rules.
Asset Allocation Still Drives Outcomes
If there’s one thing that I’ve learned over many years of fruitful investing (backed by multiple long-running studies) is that CORRECT asset allocation explains a significant portion of how “viable” your portfolio is.
For example, you could have your portfolio consist of:
- Stocks / funds / ETFs
- Bonds (corporate, governmental, individual or via a fund/ETF)
- Real estate
- Precious metals
- Cash
- Crypto
And so forth. I’m personally invested in all of these things, and because of it, I’ve never lost money in a single year in my full portfolio.
Sure, in any given year, crypto could be at a significant loss (or profit), or my real estate could be down in total value, or the bonds could be, or my PHP cash could be worth less or more VS USD/euro, etc. – but on the whole, it’s never been negative.
And that’s EXACTLY the point of diversification. If I were, say, fully into crypto, or fully into real estate, or whatever – and that asset has a shit year, or even decade, I’d be worried sick because my full net worth would be in jeopardy.
As it stands, however – all of these asset classes would have to lose significant value before the whole portfolio would be compromised. While that’s possible, it’s also highly, highly unlikely.
The balance between your assets matters more than trying to time individual markets. In fact, trying to time individual markets is a fool’s game and you should steer clear of it.
As an expat, your risk tolerance may shift depending on income stability and residency status. But the logic behind allocation remains completely intact.
Compounding Still Works Quietly
Whether you live in Singapore or São Paulo, long-term growth depends on consistent reinvestment. Returns that remain invested generate additional returns over time.
Welcome to the magic of compounding. If you use it properly, it’ll work financial magic in your favour. If you misuse it (or rather, let someone else use YOU as their source of compounding!), you’ll quickly go broke.
Time in the market beats timing the market, ANY day of the week. It remains infinitely more powerful than attempting to predict short-term fluctuations.
That simple dynamic continues operating smoothly across all international jurisdictions.
This forms the foundation of building robust savings abroad for expat families, and it’s rather easy to have it work in your favour:
- Step 1: Maintain consistent contributions.
- Step 2: Automate your dividend and return reinvestments, or just do it manually if you want more control.
- Step 3: Allow long-term wealth compounding to run uninterrupted.
I cannot stress enough how important this is, and how wealthy you can get if you get (even moderate) positive returns year after year, for decades on end.
What Changes: Taxation
I really goddamn dislike taxes. I’m sure nobody likes them, but man … It’s one thing to dislike taxes because they take a large part of your income away, but it’s another when you disagree with the underlying concept on a fundamental, philosophical level.
Most people do not realize that taxes are the single largest expense in your entire life. More than rent, buying a house, sending your kids to private schools, medical bills, and so on.
Taxes, especially from Western nations, rob you blind, to fund failing governments.
Anyway, I won’t go into it much more. Suffice to say, taxes suck, and you should do your utmost to minimize the amount you have to pay.
How does this apply to investing as an expat?
Well, it depends on where you live and how you make money!
- Some countries tax residents on their worldwide income. I would advise you to not live in those.
- Some tax only locally sourced income. This is where you want to be, because (I assume) you have international income, and as such you won’t be taxed on them. 0% taxes on what you earn. Let that sink in.
Keep in mind that tax residency rules vary significantly and often depend on days spent in a country or your primary center of economic interest.
Many countries operate on the principle: if you spend more than 183 days in their territory, you’re a tax resident.
That’s why some nomads choose to spend their time between two main bases, with a week in a vacation spot thrown in, so they never spend more than 180 days in one nation, and as such, are never a tax resident.
A special caveat for citizens of the Land of the Free (always makes me laugh): your taxation is based entirely on citizenship rather than residency.
That means your global income reporting obligations continue even while living abroad, creating unique tax implications of expat investing.
You could be a US citizen and have lived in Panama for over 30 years, never have gone back to US soil, and STILL have had to pay taxes every single year to your corrupt, incompetent, greedy government.
Global Tax Systems Comparison
| System Type | Tax Basis | Key Exposure |
| Citizenship-Based | Passport held | Worldwide income taxed regardless of actual residence. Only applies to US citizens, and those from Eritrea. Yes. |
| Residency-Based | Physical presence | Worldwide income taxed after matching local day-counts, usually 183 days. |
| Territorial | Local source | Only income generated inside the physical border is taxed. The best option, always live here. |
Additional reporting requirements apply to certain foreign financial accounts above specified thresholds.
Other countries determine tax obligations based strictly on local residency tests.
Understanding your precise status under local tax residency explained for expat families is completely non-negotiable.
Investment Account Access
Now let’s move on to a more practical restriction: your physical residency can heavily affect your brokerage access.
Many financial institutions restrict services based on where their clients physically reside.
Compliance regulations, including anti-money laundering frameworks and local securities laws, frequently limit product availability for non-residents.
- For example: U.S. citizens living abroad sometimes face sudden account closures or limited product access due to reporting regulations.
- Conversely, certain European investment products are heavily restricted for retail investors who do not meet strict regulatory definitions.
These local variations represent the core expat stock market rules you must navigate.
That being said, you could quite easily circumvent this. I’m speaking purely from personal experience here and anecdotal evidence, so do your own research.
- You could just set up your residency in a European country, open a brokerage account, invest there, and then just fuck off and change your residency. I’ve done this for many years, with zero problems.
- HOWEVER! Sometimes, it depends on the broker, you may need to update your information, and provide a recent proof of address. That requires you to either go back to the country in question, renew your residency there, get a proof of address, fix your account, and fuck off again.
- OR, and I’m certainly not advocating this, for legal reasons, this is just a hypothetical, you could just take an old proof of address and change the date on it. But again, I’m not saying you should do that, because it’s probably illegal.
Currency Exposure
Another fun (or at least interesting) part about investing while living abroad is currency exposure.
Living abroad introduces complex currency considerations that domestic investors rarely think about deeply – because it obviously doesn’t affect them.
If you earn income in one currency but hold your core investments in another, exchange rate fluctuations will directly affect your family’s real purchasing power.
Currency risk does not always need to be completely hedged, but it must be understood.
This exposure is a vital element to track within your broader overseas investment strategies.
For example, if you plan to settle down permanently in the country where you currently live, holding assets aligned with that future spending currency can reduce your long-term volatility in real terms.
From my personal experience, I can tell you for a fact that currency exposure can be a blessing and a curse, at the same thing.
Let’s look at the exchange rate PHP to Euro. A couple of years ago, one euro was roughly 60 PHP. Now, it’s over 70.
- The Blessing: That means that on the one hand, my euros go 17% further now than they did before. When I send over 1k, I have an extra 10.000 PHP compared to what I’d get years ago. Pretty great profit, right? And yes, for daily spending and new investments, this is wonderful. Geo-arbitrage at its finest.
- The Curse: However, it also means that my PHP investments are now worth less compared to when I bought them – if you look at their value in euro. In PHP my real estate, for example, has gone up well (plus the many years’ worth of rental income), but even so, the value in euro is barely threading water. Of course, this is only a problem if I turn my PHP back into euro – something I now cannot do whenever I want.
Conclusion
In summation, investing as an expat isn’t all that complicated.
Despite all the potential additional regulatory layers, the core truth of wealth building remains completely steady.
Expat life introduces administrative and legal adjustments, but it does not rewrite the foundational principles of expat finances.
Investing is about owning productive assets over time, aligning your risk tolerance with clear goals, and avoiding unnecessary costs and emotional mistakes.
That’s it. Get that right for decades, and everything else is noise.