Why Traditional Retirement Planning Fails Expats

Key Take-Aways
- Traditional retirement planning assumes a single country, single tax system, and stable long-term residency.
- Successful expat retirement planning on the other hand requires flexibility, solid planning, jurisdiction awareness, and globally diversified assets.
- Us expats face issues like cross-border tax rules, currency risk, and pension portability issues that standard advice rarely addresses.
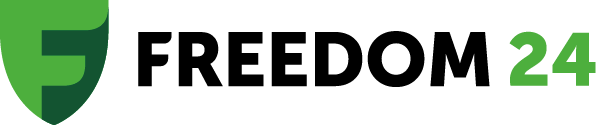
Most traditional retirement advice is built around a quiet, unexamined assumption: you will live, work, and eventually retire in the exact same country.
For globally mobile individuals and international families, that foundational assumption falls apart almost immediately.
If you are in any way like me: currently raising children in Latin America and Asia while holding legal citizenship somewhere else, earning income across multiple currencies, and potentially planning another major international move down the road, the standard financial blueprint simply does not fit your reality.
It is not that mainstream financial advice is inherently wrong; it is just dangerously incomplete (it’s also, in my opinion, wrong for the modern day and age, but we’ll talk about that in a bit!).
Let’s break down exactly why traditional retirement fails and how you can map out a highly resilient, cross-border financial future.
The Flawed Single-Country Assumption
Traditional financial building models are built entirely on a highly predictable, linear life path:
- You are expected to work in one domestic economy for 30 to 40 consecutive years
- Contribute diligently to a single national pension system
- Accumulate any investments you may have in, hopefully, tax-advantaged accounts operating under one cohesive tax code
- Finally, you retire locally and draw your distributions in the exact same currency you used to pay your bills for decades.
There are a shitload of issues facing the traditional retirement system – like the fact, the FACT, that Western governments are so strongly in debt and that the eligible retirement age population is growing at such a rate that it’s mathematically impossible for the current system to continue on.
If you’re currently relying on traditional requirement to keep you going during your old age, I fear you’re in for a nasty surprise the next few decades.
But that’s a topic for another day – one that warrants a lot of attention and, in my opinion, is an extremely strong reason to move out of the Western world and stop relying on this outdated system.
Anyway, let’s just assume the traditional retirement system is still valid, and that’s what we’ll compare our expat options to.
Expat life completely disrupts every single stage of that process.
You might split your primary working years across three or four distinct countries over a twenty-year period.
This creates unique challenges if you’re attempting comprehensive expat retirement planning on your own, but it’s a crucial part of how expat families build long-term stability.
Take a look at this table, which shows you exactly the difference between traditional and nomad retiring – and why, in my opinion, us expats have it so much better.
| Retirement Phase | Standard Model | The Expat Reality |
| Working Income | Single domestic currency | Multi-currency income sources |
| Tax Framework | One tax code for life | Overlapping tax jurisdictions (if you do it well, very low taxes!) |
| Asset Location | Domestic bank or brokerage | Accounts and property scattered globally |
| Endpoint Geography | Retiring in the same country | Moving to a new target nation |
Pension Portability Is Not Automatic
Public state pension systems are almost universally based on strict lifetime contribution histories. You need to be a slave of the system for X amount of years, before you’re allowed to leech off the contributions of young people forced to be a slave of the system.
Your ultimate eligibility depends heavily on meeting specific minimum years of active contributions and hitting defined age requirements.
In many countries, if you choose to emigrate before reaching that minimum contribution threshold, you may lose your accumulated entitlements entirely.
Fortunately, some countries maintain formal international agreements to coordinate social security coverage. These bilateral frameworks help prevent double contributions and protect your benefit rights when moving.
If you happen to move between countries that lack these specific bilateral agreements, your accumulated contribution years will not combine.
This can easily lead to highly fragmented entitlements. Navigating these fragmented systems is a core aspect of handling expat pension planning properly, ensuring you do not leave valuable money on the table when moving between different systems.
All of this “maybe”, “if”, “happen to”, “eligible” and “depending on” gives me the creeps. If you add all of this to the fact that your country will be in serious trouble within the next few decades when it comes to retirement pay-outs (do some research if you don’t believe me – you’ll be shocked), it only leads to one conclusion: do NOT rely on traditional pensions of “social security” whatsoever.
The 4 Percent Rule Was Never Designed for Global Mobility
The highly popular, standardized withdrawal strategies frequently cited in retirement seminars are based heavily on historical market data.
These classic formulas assume a portfolio denominated in one currency, living expenses anchored in that identical currency, and a retirement spent entirely within that specific economic environment.
When you layer in cross-border taxation, foreign exchange exposure, and the logistical realities of retiring overseas challenges, the baseline mathematical models shift completely.
This reality does not invalidate the importance of maintaining a disciplined withdrawal strategy. It simply means your financial strategy must be adapted to your unique geographical footprint.
Your plan should always reflect where you actually plan to spend your time, not where an outdated academic model assumes you will live.
Inflation Is Not a Universal Metric
Inflation used to scare the shit out of me, and you should feel the same, if you’re relying on standard, traditional retirement planning.
(This is another large topic, but in short: your pension, if you get it, and that’s definitely not guaranteed, will roughly be the same amount every month, whereas inflation in your home country is almost certainly going to strongly rise in the next few decades. That means that while you may keep receiving the same nominal amount, your net purchasing power will decrease.)
Mainstream financial models almost always bake in a generic, domestic inflation rate when projecting your future purchasing power.
In reality, inflation rates vary wildly from one country to another based on local monetary policy and supply chains.
If you choose to settle in a country suffering from high local inflation while your core assets remain tied to a foreign currency, your real-world purchasing power can erode much faster than your financial planner anticipated.
Conversely, and this is what I do – you can use this to your advantage by practicing geographic arbitrage, moving to locations with a lower cost of living to instantly grow the value of your portfolio.
For example: I’m currently in the Philippines (won’t be for much longer, but might return permanently in the future, let’s see) where the local currency is much weaker now vs the euro, compared to a decade ago when I first came here.
That means that a lot of my money is now 20% more valuable here. With the same amount of euros, I can buy 20% more products, investments and services. Geo arbitrage at work, in my favour – and you can easily achieve this too.
A Better Framework for International Wealth
So if traditional models fall short, what actually works for an international family?
The answer lies in building a flexible, location-independent financial foundation. A global retirement strategy centered around true geographic optionality:
- Focus on building globally diversified investment portfolios that are not tethered to the health of a single domestic economy.
- Make sure your portfolio includes income producing assets, such as rental units, dividends, bonds, and so on.
- Purchase property across the world, in rising economies such as Southeast Asia and Latin America, in nations where they respect property laws.
- Put your economic center and your residency in a country where they do not tax international income. If you can avoid paying your shithole Western country 50 to 70% of your income for decades, and invest that amount diligently, it’s almost impossible not to become wealthy.
- Keep emergency funds in liquid cash across secure international banking hubs.
By doing this, you set yourself up for a highly flexible, highly resilient and financially independent retirement.
You ensure you’re not dependent on a single (probably failing) government or nation to take care of you when you most need it.
This is exactly what being a successful expat dad is about: providing your family with a robust structure that transcends borders and cannot be blown to pieces at the whim of one government or by any random event in your home nation.
Do you know anyone who relies on traditional retirement who can say the same?