🏢Investing in Foreign Real Estate: A Guide for Expat Fathers

TLDR
- Foreign property assets offer excellent global property diversification, steady rental yields, and long term stability for international households.
- Every country enforces unique international property laws, local tax regulations, and specific restrictions on foreign land ownership.
- Profitable investing relies heavily on choosing premium micro locations, verifying clear title deeds, and analyzing local population shifts.
- Managing a real estate portfolio from across a border introduces currency fluctuations, property management costs, and regulatory adjustments.
- The most successful real estate purchases support your long term family milestones rather than just chasing speculative appreciation.
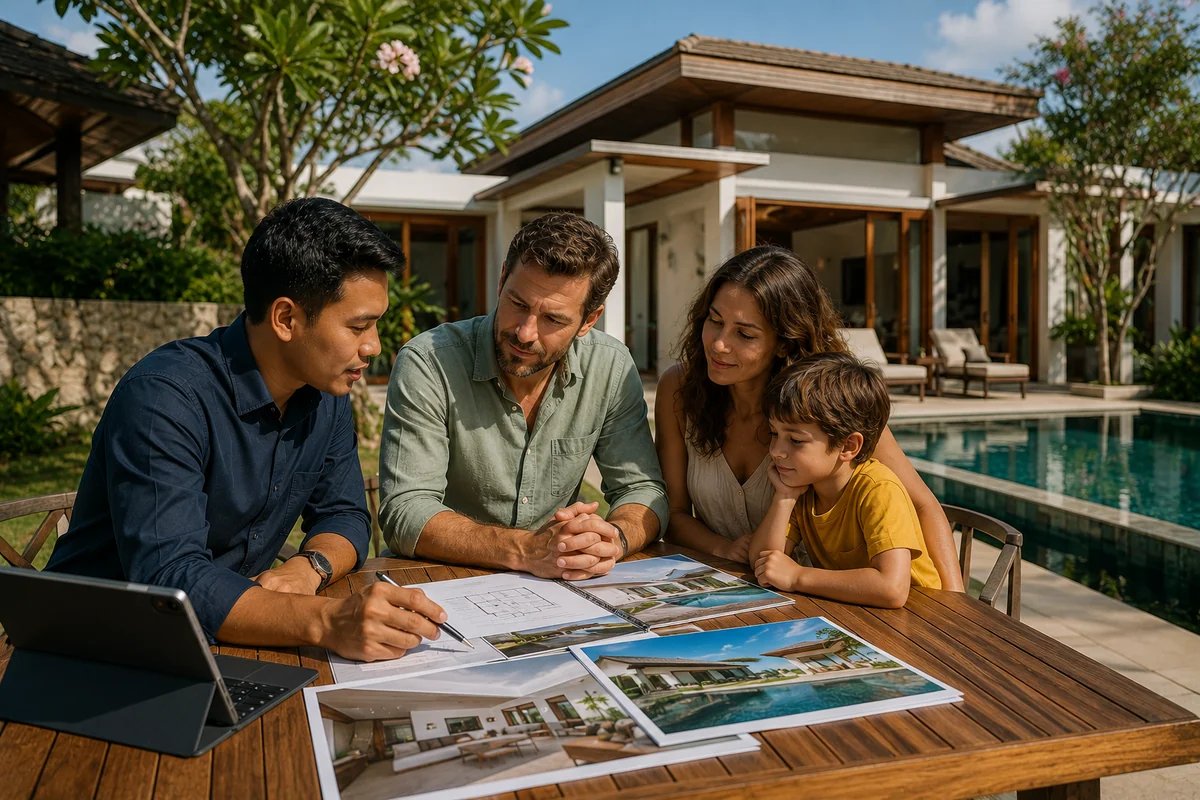
For many fathers raising a family overseas, there comes a clear moment when paying rent every month starts to feel a bit too temporary. You have finally found your feet in the local community, made fantastic friends, established stable routines, and started looking past your next residency stamp.
Naturally, big financial questions begin to surface. Should you plant deeper roots by purchasing a home, or look into buying property abroad as a way to generate passive rental income overseas? Could acquiring international real estate become a primary pillar of your long term plan to build generational wealth?
These are excellent questions to ask because purchasing real estate outside your home country can be highly rewarding yet incredibly complex. Navigating this path requires balancing different legal frameworks, local tax requirements, and foreign mortgage setups while maintaining your day to day family stability.
🎯 Understanding Why You Want to Buy
Before browsing online property listings or touring neighborhoods, you need to be entirely honest about your core investment motivation. Not every international property asset serves the same practical purpose for an expat household.
Some fathers purchase a spacious villa because they plan to stay in a specific city for a decade while managing their family routines. Other fathers look for compact apartments aimed at securing reliable cash flow from young professionals or travelers.
Expert Tip
Separate your emotional lifestyle desires from your hard financial targets before looking at a single house. A perfect family home rarely makes for a high yield investment property.
| Investment Focus | Best Property Match | Primary Target Audience |
| Pure Cash Flow | Urban apartments, city studios | Real estate for digital nomads |
| Family Stability | Suburban houses near schools | Long term local residents |
| Future Retirement | Coastal villas, quiet country homes | Vacationers and expats |
Understanding your primary target helps you filter out bad options before risking your capital. Clear targeting ensures your property plays a supportive role as you figure out how to structure your personal finances while living overseas, keeping your portfolio secure as you focus on long term wealth creation.
⚖️ Learn the Ownership Rules First
A massive mistake a foreign buyer can make is assuming that real estate transactions work the exact same way all over the globe. Local property laws are highly regional, and assuming things are straightforward can lead to major legal headaches.
Certain countries invite foreign buyers with open arms and zero restrictions, while neighboring states might completely ban non-citizens from owning specific types of land. For example, the detailed regulations around owning land in Latin America require careful structural setups that differ wildly from European rules.
- Absolute Ownership: Non-citizens hold identical property deeds and land titles to local residents.
- Restricted Ownership: Foreigners can legally own individual apartment structures but cannot directly own the ground beneath them.
- Trust Requirements: Buyers must utilize specialized bank trusts or local corporations to secure their real estate assets safely.
Before spending money on flights, background checks, or initial reservation fees, verify exactly what foreign buyers are legally permitted to hold. Taking the time to understand these boundaries protects your capital and aligns with getting your essential family paperwork fully in order before making major commitments.
🔍 Due Diligence Is Non-Negotiable
Every real estate purchase requires careful verification, but international transactions demand a completely different level of analytical scrutiny. You must verify that the property title is entirely clean, free of historical debt, and legally cleared for an immediate transfer.
Hiring an independent, bilingual real estate attorney who represents only your interests is an absolute necessity during this process. Do not rely on the seller’s legal team or a casual translation tool to review complex multi page purchasing contracts.
- Title Searches: Verify that the seller is the sole legal owner and that no family land disputes exist.
- Debt Verification: Check that all historic utility bills, local taxes, and community fees are paid in full.
- Building Permits: Ensure all structural extensions and historic renovations were completed with official municipal approvals.
When you invest outside your home market, absolute verification must always come before trust. Reviewing global housing studies shows how drastically administrative standards can vary between continents, making local legal assistance critical.
📍 Focus on Location Before Everything Else
The classic real estate phrase about location being everything is incredibly accurate when you are navigating an unfamiliar foreign market. Premium locations hold their underlying value much better during economic downturns and bounce back far faster when conditions improve.
When analyzing a specific town or neighborhood, look far past the current asking price per square meter. Look closely at local public transport upgrades, population shifts, hospital access, and the quality of nearby international schools.
A slightly more expensive apartment in a thriving neighborhood will consistently outperform a massive bargain property located in a stagnant area. Securing a property in a stable area provides immense peace of mind, making it easier for you to focus on managing family schedules without burning yourself out.
📈 Understand Local Rental Markets
Many expat fathers purchase international real estate with the explicit goal of generating a steady stream of passive income. Before making any financial assumptions about your future returns, you must study the local rental market using real numbers.
Find out exactly who is renting homes in the neighborhood and look into realistic local vacancy rates throughout the year. You need to know if your target tenants are long term local families, corporate expats, or short term travelers.
What to Look For: Look for steady, year round rental demand from multiple tenant groups rather than relying on high seasonal holiday pricing.
A modest, well located apartment with consistent occupancy will always yield better long term results than a luxury villa that sits empty for months. Keeping your income streams steady is a fantastic way to ensure you are building a stable global portfolio.
💵 Consider Currency Risk
One distinct risk that comes with buying property abroad is managing your ongoing exposure to foreign currency fluctuations. A property can easily gain value in the local currency while dropping in value when converted back to your primary home currency.
Shifting exchange rates will directly affect your monthly rental profits, local maintenance bills, and eventual sale returns. This does not mean you should skip international markets, but you must factor these currency shifts into your financial planning.
- Income Mismatch: Earning rental profits in a weak currency while paying off a property mortgage in a strong currency.
- Transfer Costs: Losing substantial percentages of your monthly yield to international banking fees and conversion spreads.
- Valuation Swings: Watching your underlying asset value change dramatically due to macroeconomic shifts.
Smart international property owners analyze their underlying real estate returns and currency exposures as two completely separate variables. Factoring in these adjustments is a great habit to practice alongside learning how to protect your money from exchange losses when moving capital across borders.
🏦 Financing Is Often Different Abroad
Many first time buyers assume that securing a property mortgage abroad will look identical to the process they went through back home. In reality, international financing options vary wildly depending on your passport, residency status, and local banking laws.
Foreign buyers often face much higher down payment demands, strict income verification steps, and shorter repayment timelines from local banks. Some buyers choose to cash out equity from assets back home, while others work with specialized international lenders.
- Down Payment Thresholds: Local banks frequently require non-resident buyers to put down 30% to 50% upfront.
- Paperwork Burdens: Preparing certified tax returns, certified bank statements, and fully apostilled identity documents.
- Interest Rate Spreads: Facing higher borrowing costs and localized loan fees compared to domestic buyers.
Understanding your realistic financing options before touring properties saves you from major disappointment later on. Securing your funding early keeps your capital structured, which fits perfectly within a smart cross-border strategy for opening multiple bank accounts.
🔧 Don’t Ignore Property Management
Owning a piece of real estate is a great milestone, but managing that property day to day is a completely different challenge. This operational hurdle becomes highly visible when you live hours away in a completely different time zone or country.
Leaky pipes, broken appliances, tenant turnarounds, and sudden emergencies will occur whether you are in the city or on an airplane. Hiring a professional property management company solves these issues, but their monthly fees must be calculated into your initial cash flow sheets.
- Maintenance Coordination: Resolving urgent plumbing or electrical emergencies without having to catch a last minute flight.
- Tenant Screening: Handling credit background checks, collecting rent on time, and managing local lease renewals.
- Legal Compliance: Ensuring your rental unit strictly follows all local housing safety laws and registration rules.
Always calculate realistic management fees into your property expenses from day one to protect your personal time. For a deeper look at keeping your physical home secure when you are traveling or living far away, see these tips on setting up smart home security.
📝 Tax Considerations Matter
Holding real estate across borders means your investments will naturally interact with multiple tax jurisdictions at the exact same time. You will likely encounter local property taxes, rental income taxes, capital gains obligations, and international reporting rules.
The main objective here is not trying to find loopholes, but understanding your exact legal obligations before making a purchase. Finding out about an unexpected foreign tax liability years down the road can completely wipe out your projected investment returns.
Cross-Border Tax Checklist
- Does your home country require you to report all foreign real estate holdings annually?
- Is there an active double taxation treaty protecting your income between both nations?
- What are the local withholding tax rates on rental profits earned by non-resident owners?
Gathering professional advice from a cross border tax specialist is worth every penny when moving significant sums of capital. Staying fully compliant preserves your wealth and aligns cleanly with structuring your annual expat tax filings without getting hit with massive surprise penalties.
🏢 Think Beyond Appreciation
It is incredibly easy to get caught up in optimistic projections about future property prices doubling over the next decade. While property value growth is a fantastic wealth building tool, relying entirely on appreciation introduces a massive amount of unnecessary risk.
Real estate markets move in cycles, interest rates shift, and local housing policies can change overnight. A much safer approach is to evaluate whether a property remains a smart investment even if its market price stands completely still for five years.
- Cash Flow Focus: Prioritizing immediate monthly rental profits over speculative future sales values.
- Multifunctional Use: Choosing properties that can serve as a future retirement base or a home for your children.
- Practical Utility: Ensuring the home provides immediate geographic flexibility and portfolio balance for your household.
Focusing heavily on immediate utility and steady rental yields protects your family from sudden market corrections. Investors can look at alternative routes like how to safely buy property abroad using entirely self-funded models to skip traditional bank overhead completely.
👨👩👧👦 How Real Estate Fits Into Family Planning
For expat fathers, major financial moves should never be made in complete isolation from the rest of the household. Buying a property intersects directly with your children’s schooling timelines, your retirement targets, and your overall family lifestyle preferences.
A home located near top tier healthcare facilities and public parks becomes incredibly valuable as your children grow up. Easy access to major international transport hubs is also a huge plus if your family travels frequently or manages businesses across borders.
A property that checks these structural boxes does far more than just protect your capital. It turns into a functional base that gives your household immense stability, which is a core part of how international families plant deep roots.
🧠 Avoid Emotional Buying
Living in a beautiful foreign country can easily cause you to make emotional real estate choices. A sunny beachfront flat can instantly feel like a dream holiday, or a historic colonial home might look like the ultimate family retreat.
There is absolutely nothing wrong with feeling a deep personal connection to a specific property or neighborhood. The dangerous financial traps arise when those warm emotions completely replace cold, hard financial analysis during the closing process.
- The Reality Check: Evaluate the property data as if you were looking at a spreadsheet for an unfamiliar city.
- The Utility Test: Ask yourself if the home remains useful to your family if your job requires you to relocate next year.
- The Pricing Test: Check if local families are paying similar prices, or if the property features an inflated expat premium.
Stripping the emotion away from the transaction helps you spot hidden property flaws and negotiate a much better deal. Historic global development data underscores how rapidly developing local neighborhoods can shift, meaning cold data must always drive your final offer.
📊 Global Property Diversification Still Matters
Even if you are incredibly enthusiastic about the local housing market, you must remember the core rule of building long term security. True financial safety comes from spreading your capital across completely different asset classes and geographic zones.
Placing your entire life savings into a single property or one foreign market exposes your household to concentrated regional risks. Changes in local zoning laws, natural disasters, or sudden political shifts can instantly impact your property’s value.
- Asset Balance: Keeping a healthy mix of liquid index funds, cash reserves, and physical real estate holdings.
- Geographic Spread: Avoiding holding all your family wealth within a single host nation or currency block.
- Risk Management: Protecting your portfolio so that a downturn in one market will not derail your family’s future.
The ultimate target of an expat real estate investment is not just collecting titles, but building a highly resilient financial foundation. Keeping your portfolio balanced ensures your family remains secure, allowing you to focus on keeping your marriage and parenting strong while moving between countries.
🏁 Conclusion
Foreign real estate can serve as an incredibly powerful tool for expat fathers looking to build long term wealth, secure geographic flexibility, and protect their families. The financial opportunities are completely real, but navigating the cross border legal steps requires a patient, disciplined approach.
Real investment success comes from committing to thorough research, protecting your downside with legal experts, and knowing exactly how a property supports your family’s goals. Focus on the core building blocks: clean land titles, top tier locations, solid rental yields, and clear tax compliance.
When you approach international real estate with a clear plan, property ownership becomes much more than just a financial investment. It turns into a wonderful, steady foundation that supports the intentional, globally minded lifestyle your family is working hard to build.